Q3 Housing Levers Update
The Rithm Take
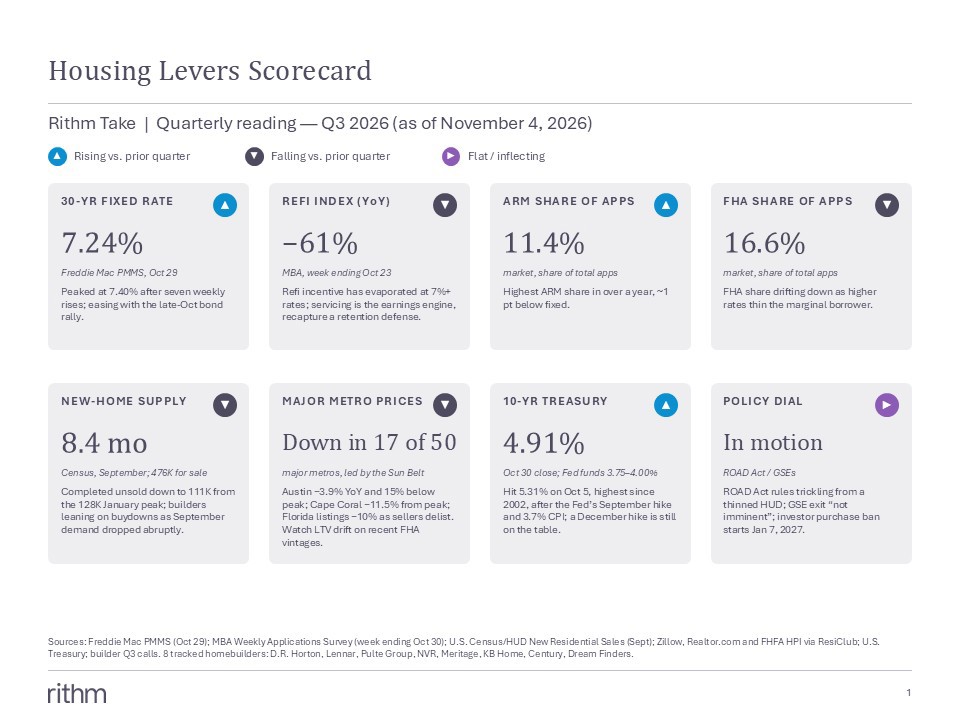
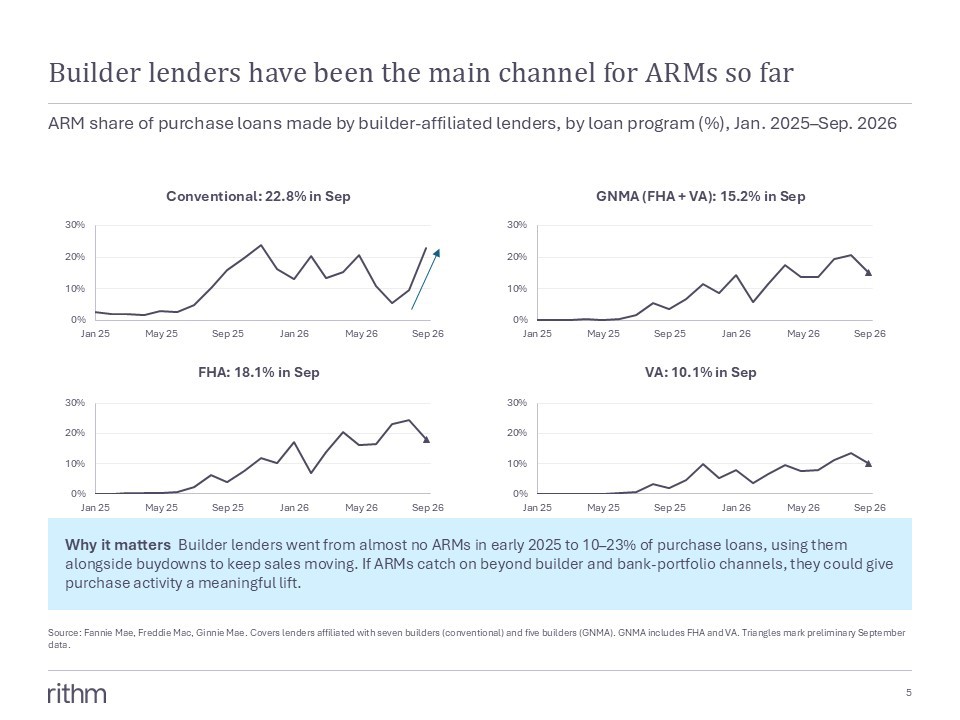
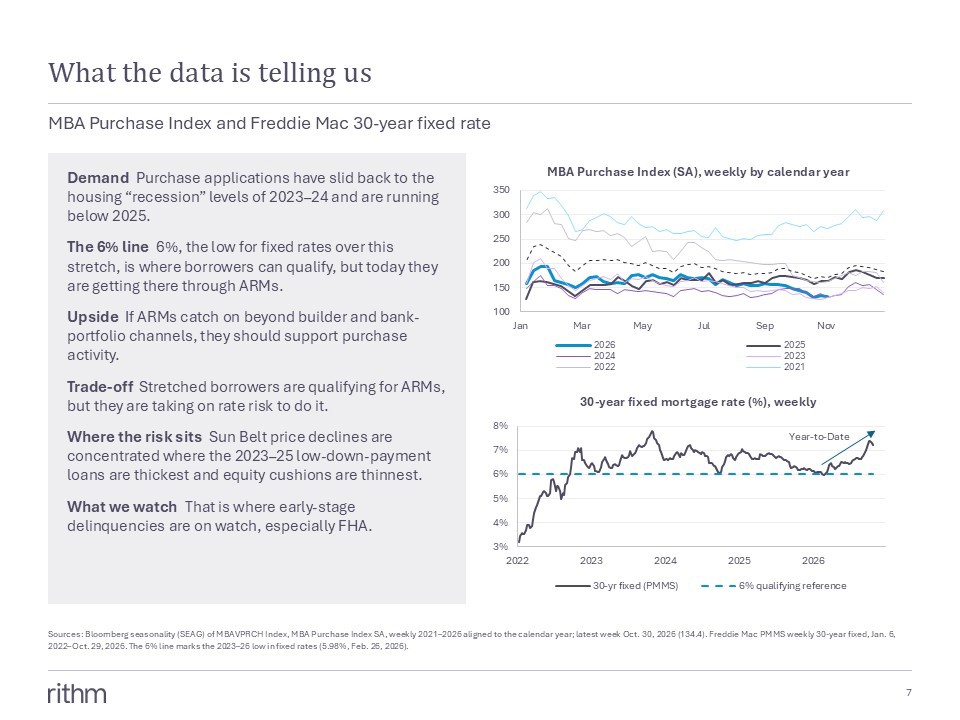
In this Rithm Take we update our quarterly coverage of housing dynamics. Fixed rates are back above 7%, and purchase applications have fallen back to their 2023–24 lows. Large builders we track sold fewer homes than a year ago. What's changing is how buyers reach a payment they can qualify for. Builders are using incentives and their own mortgage lenders to keep sales going, and adjustable-rate mortgages (ARMs) are now a regular part of how builders sell homes.
Top Takeaways
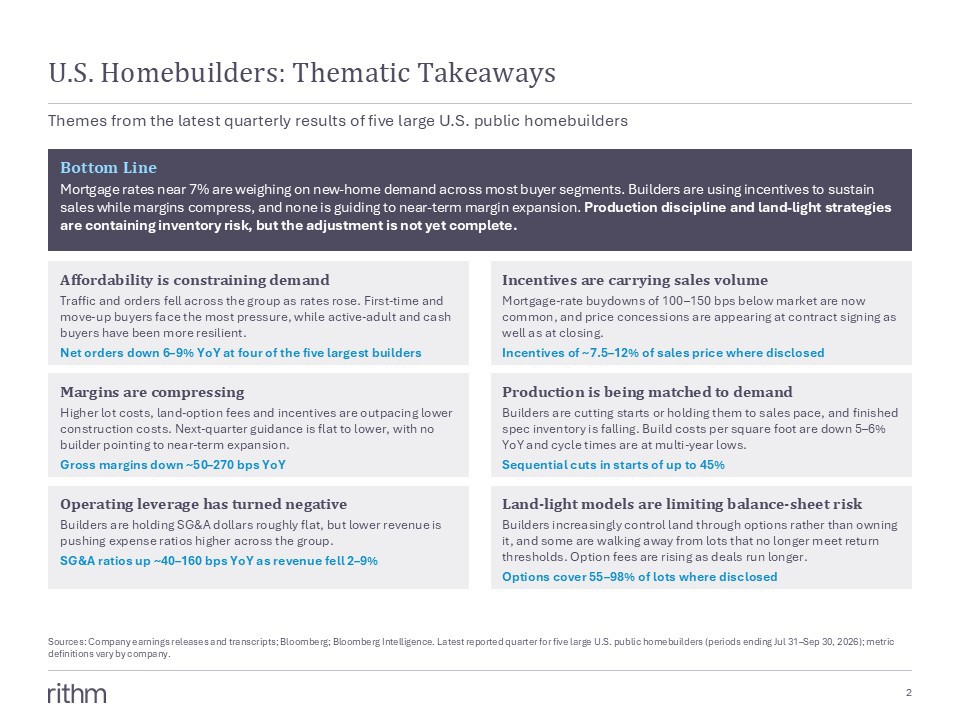
- Builders are protecting sales volume at the expense of margin. Orders are down 4–15% YoY at all eight large builders we track. Rate buydowns of 100–150 bp and incentives worth 7.5–12% of the sale price are holding sales up, while gross margins are down as much as 270 bp. No builder is guiding to margin expansion in the near term.
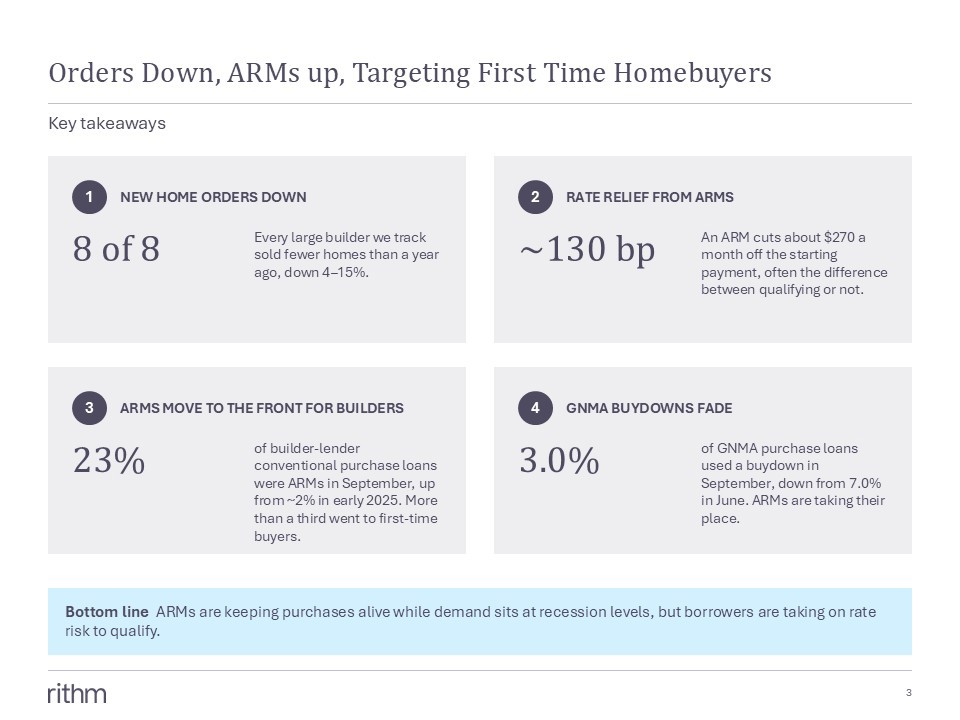
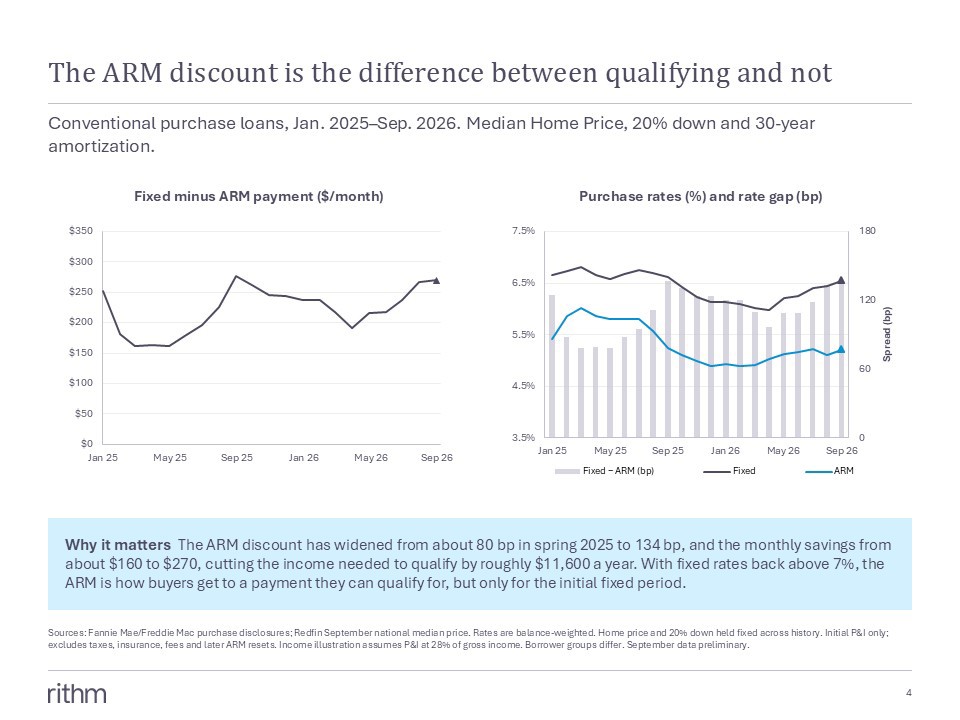
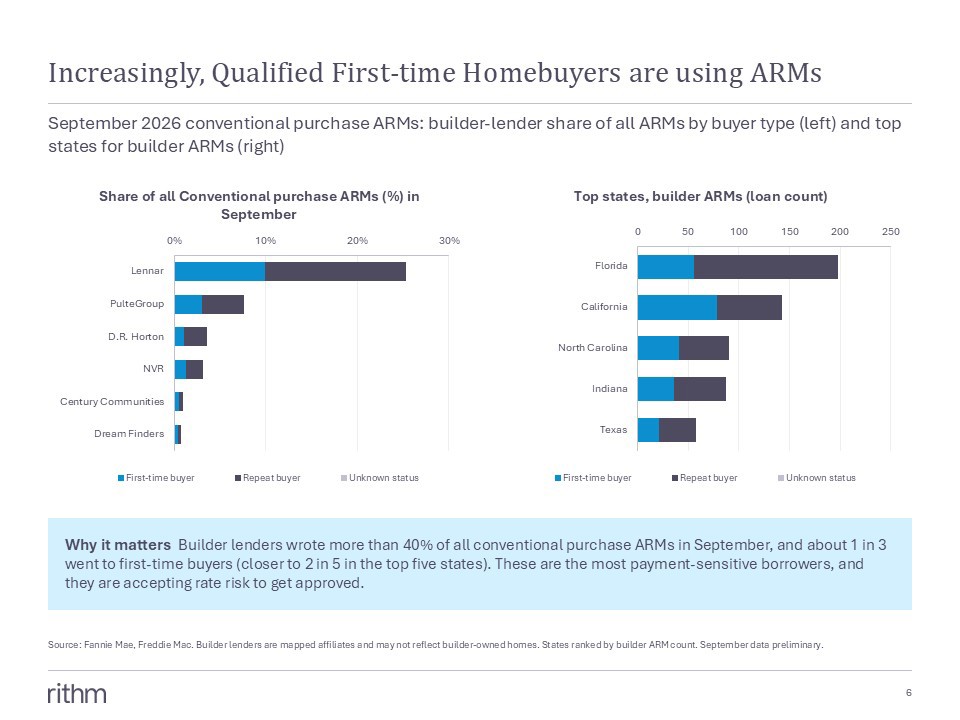
- ARMs are the new affordability tool, and builder lenders are driving the shift. The ARM discount to a fixed rate has widened to about 134 bp, which takes roughly $270 off the monthly payment. ARMs rose from about 2% of builder-lender conventional purchase loans in early 2025 to 23% in September. Over the same stretch, GNMA buydown use fell from 7.0% in June to 3.0%. Builder lenders wrote over 40% of all conventional purchase ARMs, about a third of them to first-time buyers.
- Risk is building up among the most payment-sensitive borrowers and markets. First-time buyers are taking on rate risk to qualify. Prices are falling in the Sun Belt markets with the most 2023–25 low-down-payment loans (Austin −3.9% YoY, Cape Coral −11.5% from peak). We are watching early-stage FHA delinquencies in those markets which would be the first place for stress to show.